At Home with Team Gabriel

You’ll find our blog to be a wealth of information, covering everything from local market statistics and home values to community happenings. That’s because we care about the community and want to help you find your place in it. Please reach out if you have any questions at all. We’d love to talk with you!

Oct. 28, 2026

360° Virtual Tour 18 Lucks Way, Bolton, CT

Oct. 28, 2026

Team Gabriel | Open House | 18 Lucks Way, Bolton, CT

Posted in Open House
Oct. 28, 2026

Appraisal Came In Low in Connecticut? Your Options

By Lori Gabriel · Oct 28, 2026

Your first move is to find the contract's appraisal and financing deadlines, then ask your lender for the exact loan calculation. From there you choose among challenging the value, renegotiating the price, adding cash, or terminating if the contract permits. A missed deadline can cost you options that the appraisal number alone never would.

What happens when an appraisal comes in low in Connecticut?

When an appraisal comes in low in Connecticut, your contract does not automatically cancel, but your loan usually shrinks. Lenders can base the loan on the lower of the purchase price or the appraised value, depending on the loan program, so the gap often becomes your cash to cover. You can challenge the value through your lender, renegotiate with the seller, bring more cash, or exit if your written contingencies allow it.

Key Takeaways

  • A lender's appraisal is an opinion of value used in underwriting, not a guarantee that the home is worth the contract price, so a low number changes your financing before it changes anything else.
  • On a $500,000 contract that appraises at $480,000 with an 80% loan, the loan drops from $400,000 to $384,000 and your cash toward the price rises from $100,000 to $116,000.
  • Recent local market data shows a median sale price of $310,000 across 23 East Windsor homes sold over roughly the last 90 days, so a low number should be tested against closed sales, not assumed correct.
  • Statewide, Connecticut home sales in July 2026 ran 5.2% above July 2025, while year-to-date sales through that report sat 1.9% below the prior year, according to the Connecticut Office of the State Comptroller.
  • Your contract language and deadlines, not the appraisal itself, decide whether you can renegotiate, terminate, or recover your deposit.

What should you do first when an appraisal comes in low in Connecticut?

Pull your contract and find the appraisal-contingency deadline, the financing-contingency deadline, and the required method of notice. Those dates decide which options are still open to you.

Why do the contract deadlines come first?

A low appraisal does not cancel a Connecticut purchase contract on its own. Whether you can renegotiate, terminate, or get your deposit back depends on the written appraisal contingency, the financing contingency, the deadlines, and the notice requirements. The parties can also agree voluntarily to amend the price or other terms.

When a client's appraisal comes in short, the first thing we do together is find those dates and confirm whether the seller is entitled to see the appraisal or other lender paperwork. Missing a notice deadline can change your remedies, and no amount of good negotiating fixes that afterward.

I also review the contingency wording with your closing agent, since the exact language controls. If a seller ever disputes your right to your deposit, that is a genuine legal dispute, and it is the point to bring in a real estate attorney.

What should you ask your lender right away?

Ask your lender for the exact loan-to-value calculation, because the appraisal creates two separate questions: whether the market value was understated, and how much your loan program will lend. Request these in writing:

  • The new maximum loan amount under your program
  • The cash you now need toward the purchase price
  • Any new underwriting conditions
  • Whether a new appraisal is permitted
  • How the lender handles a reconsideration of value and how long it takes

It also helps to keep the appraisal in perspective. According to the Consumer Financial Protection Bureau, it is an opinion of value for the lender. It is not a municipal tax assessment, a prediction of future resale value, or an independent legal ruling on fair market value.

How does the appraisal gap math work, and what does local data say?

The gap is the amount the contract price exceeds the appraised value, but your extra cash is usually a different number because the loan shrinks too. Here is a simple arithmetic illustration, not a market statistic or a universal lending rule.

What does a $20,000 gap look like on a $500,000 purchase?

Assume an $80% loan against the lower of price or appraised value. The price exceeds the appraisal by $20,000, but because the loan also drops by $16,000, your added cash toward the price is $16,000.

Item Amount
Contract price $500,000
Appraised value $480,000
Price above appraised value $20,000
Loan at 80% of contract price $400,000
Loan at 80% of appraised value $384,000
Cash toward price, original plan $100,000
Cash toward price, after low appraisal $116,000
Increase in cash needed $16,000

That table excludes closing costs, prepaid items, reserves, and any lender-specific requirements. Your lender runs the real version.

Here is how negotiation changes the same example:

  • Seller drops the price to $480,000: the loan stays at $384,000, your cash toward the price is $96,000, and the gap is gone.
  • Seller drops to $490,000 (an even split): the loan stays at $384,000, your cash toward the price is $106,000, and the extra you bring is $6,000 instead of $16,000.
  • No price change: you bring the full $116,000 toward the price.

Does local market data change how you respond?

Yes, because appraisers build value from closed sales, and your response should be built the same way. Recent local market data shows a median sale price of $310,000 for East Windsor homes sold over roughly the last 90 days (23 sales), with 11 homes for sale now and 7 new listings in the last 30 days. Median prices vary widely from town to town across North Central Connecticut:

Source: aggregated public listing data, trailing 90 days, as of October 2026.
Area Median Sale Price
East Windsor $310,000
Ellington $417,500
Enfield $345,000
New Britain $323,000
Newington $370,000
South Windsor $436,000
Suffield $515,000

These are area-level medians. An individual home's value depends on condition, street, build year, and timing, which is why a comparable sale in one town rarely proves value in another.

For statewide context, the Connecticut Office of the State Comptroller's September 1, 2026 economic update reported that July 2026 home sales were 5.2% higher than July 2025, while year-to-date sales were 1.9% below the same period in 2025. A September 2026 Berkshire Hathaway HomeServices report, covered by Connecticut Insider on October 13, 2026, put statewide prices through September 2026 about 6% above a year earlier. When prices are rising, the closed sales an appraiser relies on can trail what buyers are paying today. That is general context, not a verdict on your appraisal.

What are your options after a low appraisal?

You generally have four: challenge the value, renegotiate, bring more cash, or terminate if your contract permits. You can combine them, and which ones are available depends on your deadlines and loan program.

How do you challenge a low appraisal?

Ask your lender for a reconsideration of value. The request goes through the lender, not directly to the appraiser, and it works best when it is built on verifiable facts. Useful support includes:

  • Recent closed sales in the same town or a competing submarket that the appraiser did not use
  • Documentation of finished square footage, permits, and renovation invoices
  • Factual corrections, such as wrong square footage, wrong bedroom or bath count, or omitted improvements
  • Evidence that the appraiser's comparables differ materially in acreage, condition, location, outbuildings, or finished space

Sold prices carry the argument, not asking prices or opinions. A sale in another county rarely persuades, so use closed sales that are truly comparable. Septic versus sewer, lot size, renovation level, and commute patterns all affect comparability.

A complaint about an appraiser's professional conduct is a separate track. The Connecticut Department of Consumer Protection handles licensing and complaints, and the department lists a Real Estate Appraisal Unit among its programs and services. A complaint does not guarantee a revised appraisal or protect your contract deadlines.

Can you renegotiate with the seller?

Yes, but the seller is not obligated to lower the price unless your contract says otherwise. The common structures are a price reduction to the appraised value, splitting the gap, the buyer covering the gap in cash, or adjustments to credits, repairs, or timing within lender limits.

A seller has a reason to negotiate, because the next buyer's lender will also order an appraisal. If the comps do not support the price, relisting does not make that problem disappear. I cover the pricing side of this in pricing a North Central Connecticut home in a split market.

Should you bring extra cash or agree to cover a gap?

Only if the number still makes sense for you at the price you are paying. Some buyers write appraisal gap coverage into the offer to compete. If you do, set a firm ceiling in advance and confirm with your lender that you can actually fund it. Waiving or limiting protections is a real trade-off, much like the one I outline in whether to waive the home inspection in Connecticut.

Can you walk away and keep your deposit?

Only if your contract gives you a termination right and you use it correctly. That depends on the appraisal contingency, the financing contingency, the deadlines, and the notice method. If those protections were waived or the deadline has passed, walking away can put your deposit at risk. Read the language before you decide.

Can you get a second appraisal or switch lenders?

Possibly, but treat both as long shots to confirm, not plans to count on. Ask your lender whether a new appraisal is permitted under your program. A different loan structure or lender may be feasible, but it can restart timelines that your contract deadlines do not pause.

Your specific number depends on your loan program, your cash position, and your contract dates. That is exactly the conversation I walk my clients through before they respond to the seller.

If you want to see what other clients say about working with me, you can read my reviews on Google and Zillow.

FAQ

What happens if the appraisal is low in Connecticut?

Your lender will typically lend against the lower of the price or appraised value, so you will need more cash or a changed deal. Your contract does not automatically end. Your options are to challenge the value, renegotiate, add cash, or terminate if your contingencies allow it.

Can I cancel the contract if the appraisal comes in low?

Only if your written contract gives you that right and you meet its deadline and notice requirements. Whether your deposit is protected depends on the appraisal and financing contingencies, so review that language right away.

Can the seller refuse to lower the price after a low appraisal?

Yes. Unless your contract says otherwise, the seller can say no. Many sellers negotiate anyway, since a new buyer's lender will order its own appraisal.

What documents should I give the lender for a reconsideration of value?

Give your lender factual, verifiable support: closed comparable sales the appraiser did not use, proof of finished square footage, permits, renovation invoices, and corrections to errors in the report. Also show where the appraiser's comparables differ materially from your home. The request goes through the lender, not the appraiser.

Can the buyer and seller split the appraisal gap?

Yes, if both agree in writing. In the example above, a $10,000 price cut on a $20,000 gap leaves you covering about $6,000 more cash toward the price instead of $16,000, because the loan is still based on the appraised value. Your lender must accept the revised terms.

If your appraisal came in low in Connecticut, the next 48 hours matter more than the number itself. Know your deadlines, get the lender's exact math, and build any challenge on closed sales. I work across North Central Connecticut, Western Massachusetts, and South Florida, and I pull comparables from the market your home sits in, because Connecticut sales do not prove value in Hampden County or Miami-Dade. When you are ready to run your own numbers, schedule a consultation with Team Gabriel.

About Lori Gabriel

Lori Gabriel is a Broker (ABR, CRS) and leader of Team Gabriel, serving buyers and sellers across North Central Connecticut, Western Massachusetts, and South Florida.

Coldwell Banker Realty · 860-926-5101

Equal Housing Opportunity. Team Gabriel at Coldwell Banker Realty. Regulated by the Connecticut Real Estate Commission. This article is general information, not legal, tax, or financial advice; confirm your own numbers with your closing agent, tax advisor, or lender. By providing contact info, visitors consent to telemarketing/automated calls and texts from teamgabriel.net; message and data rates may apply.
Posted in Buyers
Oct. 26, 2026

List a Home in Suffield? How to Choose the Right Agent

By Lori Gabriel · Oct 26, 2026

The best agent to list a home in Suffield is the one who prices from closed sales, explains why each comparable fits your property, and understands how Suffield's acreage, location, and housing age change value. Ask to see recently sold homes, not just asking prices, before you sign a listing agreement.

Who is the best agent to list a home in Suffield, CT?

The best agent to list a home in Suffield is the one who sets your price from homes that have actually closed nearby, explains why each comparable fits your property, and can show you the competition on the market right now. "Best" should be measured by pricing method, local knowledge, communication, and marketing plan, not by a slogan. Below I explain how I evaluate those standards and how Team Gabriel at Coldwell Banker Realty approaches pricing from day one.

Key Takeaways

  • Recent local market data shows a median sale price of $515,000 for homes sold in Suffield over roughly the 90 days through October 2026, and that figure is an area-level median, not a value for your house.
  • In that same window, 57 homes sold in Suffield, and 32 homes are for sale now, so your home competes with a real set of alternatives.
  • Suffield's median sale price sits well above nearby towns such as South Windsor ($436,000) and Ellington ($417,500), so neighboring-town sales are context, not automatic comparables.
  • A credible listing price starts with closed sales adjusted for lot size, age, condition, and location, then checks active and pending listings for competition.
  • A strong listing presentation shows you every comparable and the reasoning behind it, so you can judge whether the suggested price is realistic.

How should an agent price a home in Suffield?

An agent should price your Suffield home from closed sales first, then use active and pending listings to understand the competition. Asking prices show what sellers hope to get. Closed sales show what buyers actually paid.

I always tell sellers to look at what homes have really sold for in their area before settling on a number. It sounds basic, but it is the step that separates a defensible price from a hopeful one. If you want to see where sellers go wrong, my breakdown of real estate pricing mistakes sellers make in CT covers the common ones.

Why do closed sales beat asking prices?

Closed sales are the only prices that both a buyer and a seller agreed to. A listing that has sat at a high asking price tells you very little, and expired or withdrawn listings are a warning about pricing or marketing, not evidence of value.

When I build a price opinion, the order is:

  1. Closed sales from the most recent months, with the actual closing month noted for each.
  2. Pending and active listings, to see what buyers can choose instead of your home.
  3. Expired and withdrawn listings, to spot pricing traps to avoid.

Older sales get adjusted for how the market has moved since. They are not presented as today's benchmark.

Which Suffield comparables actually fit your home?

The right comparables match your home on the features buyers pay for, not just on distance. Two Suffield addresses a mile apart can sit in very different value brackets.

Suffield is not one uniform market. A careful analysis separates Suffield Center, West Suffield, North Suffield, and properties near the Windsor Locks, East Granby, Enfield, and Windsor borders. Features that usually need adjustment include:

  • Lot size and how much of the acreage is usable
  • Dwelling size, age, and quality of construction
  • Renovations, plus bedroom and bathroom count
  • Septic or sewer service and heating system
  • Outbuildings, a pool, or other site improvements
  • Road exposure and access to Interstate 91, Bradley International Airport, and the Connecticut River

Your specific number depends on your home's condition, location, and timing. That is why a local market analysis, not an online estimate, should drive your price.

What do recent Suffield sales say before you list?

Recent local market data shows a median sale price of $515,000 for homes sold in Suffield over roughly the 90 days through October 2026. That is an area-level median, so your own home's value will land above or below it depending on condition, street, build year, and timing.

The same data shows 57 homes sold in that window, and 32 homes are for sale now. That is enough sales to give a local agent real evidence, and enough active inventory that your listing needs a clear reason to stand out.

How does Suffield compare with nearby towns?

Suffield's median sits above the nearby towns in the table below, which is exactly why a nearby town's sales should not be pasted into your pricing analysis without explanation. Enfield, East Windsor, and Windsor give useful context. They are not interchangeable with Suffield.

Source: aggregated public listing data, trailing 90 days, as of October 2026.
Area Median Sale Price
East Windsor $310,000
Ellington $417,500
Enfield $345,000
New Britain $323,000
Newington $370,000
South Windsor $436,000
Suffield $515,000

If you are weighing Suffield against a neighboring market, my look at South Windsor CT real estate trends in 2026 shows how a different town's numbers read on their own terms.

Why does pricing right from the start matter?

Chasing the market down with reductions usually costs you more than starting at a supportable number. Buyers watching a listing notice a price cut, and a home that has to be marked down often sells on weaker terms than one priced correctly at the start. Before you list a home in Suffield, ask any agent you interview to defend the number with sold evidence, not with optimism.

How do you compare listing agents, and where does Team Gabriel fit?

Compare agents on method, not marketing claims: ask what comparables they use, how they adjust them, and what the marketing plan covers. A good listing presentation makes those answers easy to see before you sign anything.

What should a listing presentation include?

Ask for these before you choose:

  • Closed comparables with closing months, and a plain explanation of why each one fits your home
  • Competing active and pending listings and how yours compares
  • Adjustments for acreage, age, condition, and upgrades
  • A pricing range with reasoning, not a single unexplained number
  • A marketing plan, including photography. I explain why in whether pro real estate photos are worth it in North Central CT
  • Communication expectations, meaning how often you will hear from your agent and in what form

Ask about fees as well. Broker fees are fully negotiable and not set by law, and any compensation a seller chooses to offer a buyer's agent is optional and separately negotiable. Get what you agree to in the listing agreement, and talk it through with me directly.

What does Team Gabriel bring to a Suffield listing?

Team Gabriel at Coldwell Banker Realty has an office at 1 Mountain Road in Suffield, and I'm licensed as a broker in Connecticut and Massachusetts, with the ABR and CRS designations listed on my profile. When you list a home in Suffield with my team, the starting point is the closed-sales work above, applied to your specific property.

The team serves North Central Connecticut, Western Massachusetts, and South Florida. That matters most if your move crosses those lines, such as selling in Suffield and buying in Florida, or relocating from one market to another. Having one team coordinate both ends means local insight on each side instead of starting over with a new agent. I would not claim it makes the team "the best" on its own. The pricing method and the work behind it are what you should judge us on. For a wider view of the area, see buying and selling real estate across Central Connecticut.

How can you tell if a suggested price is realistic?

A realistic price is one the agent can defend line by line with closed sales you can look at yourself. Be cautious if the suggested number is far above every other agent's range, or if the agent leans on asking prices and an online estimate. A high number can win the listing and then cost you time on the market.

If you are ready to list a home in Suffield, the next step is a conversation about your property, your timeline, and the sold evidence around you. Schedule a consultation or call 860-926-5101, and I'll walk you through the comparables before you commit to anything.

Curious how past clients feel about working with me? You can read my reviews on Google and Zillow.

FAQ

Who is the best real estate agent to list a home in Suffield, CT?

The best agent is the one who can defend your price with recent closed sales and explain why each comparable fits your home. Look for local pricing knowledge, a clear marketing plan, and steady communication. Interview more than one agent and compare their reasoning, not just their numbers.

How do I price my Suffield home using recently sold comparable properties?

Start with homes that closed recently and match yours on lot size, age, size, and condition, then adjust for differences. Suffield Center, West Suffield, and North Suffield can behave differently, so the agent should explain which sales apply to your street and why. Active listings then show the competition you will face.

Should I price my home based on recent sales or current asking prices?

Base your price on recent sales, and use asking prices only to understand competition. Asking prices are what sellers want. Closed sales are what buyers paid. A home priced from asking prices alone can sit on the market while better-priced homes sell around it.

Does a Suffield listing agent need to understand Western Massachusetts and South Florida?

Not for every Suffield sale, but it helps if your move crosses markets. If you are selling in Suffield and buying in Western Massachusetts or South Florida, one team that works all three can coordinate timing and local advice on both ends. Team Gabriel serves all three markets.

What should a listing presentation include before I choose an agent?

It should include closed comparables with closing months, competing active and pending listings, adjustments for your home's features, a pricing range with reasoning, and a marketing plan. If an agent cannot show you the sales behind the number, keep interviewing.

About Lori Gabriel

Lori Gabriel is a Broker (ABR, CRS) and leader of Team Gabriel, serving buyers and sellers across North Central Connecticut, Western Massachusetts, and South Florida. She specializes in relocation and new construction.

Coldwell Banker Realty · 860-926-5101

Equal Housing Opportunity. Team Gabriel at Coldwell Banker Realty, Lori Gabriel, CT License REB.0756473, regulated by the Connecticut Real Estate Commission. This article is general information, not legal, tax, or financial advice; confirm your own numbers with your closing agent, tax advisor, or lender. By providing contact info, visitors consent to telemarketing/automated calls and texts from teamgabriel.net; message and data rates may apply.
Posted in Sellers, Selling a Home
Oct. 23, 2026

Should You Waive the Home Inspection in Connecticut?

By Lori Gabriel·Oct 23, 2026

Connecticut doesn't require a home inspection, but waiving one means you accept hidden defects at full price. Your inspection rights come from the contract, not a statute. A narrower contingency covering structure, major systems, and specialist tests like septic, well, radon, and foundation can keep your offer competitive while protecting you.

Should you waive the home inspection in Connecticut?

You're not required to get a home inspection in Connecticut, but waiving one means you take on every hidden defect at full purchase price. Your inspection rights come from the contract you negotiate, not from an automatic cancellation right, so a home inspection in Connecticut is only as strong as the wording in your offer. In most cases the smarter move is a narrower, well-defined contingency rather than no protection at all.

Key Takeaways

  • Connecticut does not require a buyer to have a home inspection, and the state's own Residential Property Condition Report tells buyers they should have the property inspected by a licensed home inspector.
  • An inspection contingency is a contract term, not a statutory right, and the Connecticut Bar Association model agreement ties inspections to a negotiated Research Completion Date.
  • A satisfactory general inspection does not prove a septic system works, well water is safe to drink, radon is below your chosen threshold, or a foundation is sound.
  • For a concrete foundation with cracking, staining, or crumbling, the state disclosure form points buyers to a licensed professional engineer who is a structural engineer, not a general inspector.
  • You can usually compete without waiving everything by keeping narrower, separately identified investigations, but the exact rights depend on the wording you and the seller agree to.

I get this question from buyers who are tired of losing offers, and I understand the temptation. Here's my straight answer on the home inspection in Connecticut: waiving it is a financial bet, and the downside is yours alone. Before you make that bet, you should know exactly what you'd be giving up and what middle options exist.

What does a home inspection in Connecticut actually cover, and what does it miss?

A general home inspection covers the dwelling's structural soundness and major systems, but it does not replace specialist testing for septic, well water, radon, or foundation concrete. The Connecticut REALTORS® inspection contingency addendum lists the general inspection as covering structural soundness plus plumbing, heating and air-conditioning, electrical systems, built-in pools, and remaining appliances. It lists radon testing, septic inspection, and other specialist evaluations as separate categories.

That separation matters. "Inspection" is not one universal test, and a clean general report can sit right next to a failing septic field or a deteriorating foundation.

Type of evaluation What it can tell you What it does not tell you
General home inspection Condition of the structure and major visible systems Whether a septic field works, whether well water is potable, indoor radon levels
Septic inspection Condition and adequacy of the system and any conditions that may need repair or replacement Anything about the house itself
Well-flow or yield test and water lab testing How much water the well delivers and what the water contains Condition of the pump house or the home's plumbing
Radon test Indoor radon measured against the threshold you choose Other air-quality or moisture concerns
Structural engineer foundation evaluation Whether concrete cracking or deterioration, including pyrrhotite-related damage, is a structural problem Condition of roof, systems, or mechanicals

What do you risk by waiving everything?

You lose the chance to learn about a defect before it becomes your problem. Roofs, heating systems, electrical panels, and water damage are expensive, and a waiver gives you no contractual path to renegotiate or step back once you find them.

You also lose leverage. If the report would have shown a serious issue, you'd have used it to ask for repairs or a price adjustment. After a waiver, you simply own it.

Can you keep your offer strong without waiving the inspection?

Yes. You don't have to choose between a fully unrestricted inspection and none at all. The contract can preserve narrower investigations, such as structural, roof, mechanical, environmental, septic, well, or radon review, and the Connecticut model agreement and addenda support listing those categories separately.

What are the narrower options?

  • Structural and major-systems focus: you keep the right to evaluate the things that are costly and hard to fix, and you leave cosmetic items alone.
  • Specialist-only contingencies: you protect yourself on septic, well, radon, or foundation, where a general inspector can't give you the final answer.
  • Information-only inspection: some buyers offer to inspect to learn about the home while giving up the right to ask for repairs. Whether that's workable depends entirely on how the contract is worded, and I'd want to see the language before you agree to it.
  • Tighter timelines: a shorter, clearly dated research period can make an otherwise full contingency less of a burden for the seller.

Why does the contract wording matter so much?

Because your rights and remedies live in the document, not in a statute. The model purchase agreement treats inspections, studies, and testing as buyer research that must be finished by the negotiated Research Completion Date. Miss that date or waive the category, and the protection may be gone.

Every situation is different, and the right structure depends on the home, the competition, and your budget. This is exactly the kind of thing I work through with my buyers before we write an offer. If you're weighing a contingent structure more broadly, my post on contingent offers on Connecticut homes covers how sellers see them, and if the house needs work, my take on fixer-uppers will help you decide how much risk fits.

When do septic, well, radon, or foundation concerns call for a specialist?

Any time the home has one of those features or warning signs, a general inspector shouldn't be your final word. Each one needs its own qualified evaluation, and each is worth protecting in your offer even if you narrow everything else.

Do you need a separate septic inspection?

Yes, if the home has a septic system. The standard Connecticut addendum language calls for a qualified specialist: a licensed septic installer, professional sanitary engineer, civil engineer, registered sanitarian, or appropriately certified sanitarian. The report addresses the system's condition and adequacy and any conditions that may require repair or replacement. A general inspector can note that a house has septic, but that's not the same as confirming the system works.

What about a private well?

Treat water quantity and water quality as two separate questions. A well-flow or yield test speaks to how much water the well delivers, and laboratory testing speaks to what's in it. A general inspection establishes neither one, so if the home has a well, I'd keep both protected.

Is radon testing worth keeping?

I'd say yes, because it's cheap to protect in a contract compared with the unknown it resolves. The Connecticut model agreement allows the parties to identify a radon concentration test as a specific research category. The seller's disclosure form asks whether a radon test was performed and directs the seller to attach the report if available. A prior report is useful information, but it reflects conditions on the day it was done, so decide with me whether you want your own test.

Who evaluates a suspect foundation?

If you see cracking, staining, or crumbling in a concrete foundation, or the home has a history associated with potentially defective concrete, bring in the right professional. The state's Residential Property Condition Report specifically recommends that a potentially affected foundation be evaluated by a licensed professional engineer who is a structural engineer, and it warns about deterioration associated with pyrrhotite. This is one area where I would not let a buyer waive protection to win a bidding situation. A foundation problem can affect the value and financing of the whole property.

How does this change in North Central Connecticut, Western Massachusetts, and South Florida?

The core logic holds in all three markets: protect yourself on the expensive, hard-to-see items, and be flexible on the rest. The documents and the specialist tests differ, though, so don't assume one set of rules carries across.

North Central Connecticut

Recent local market data for East Windsor shows a median sale price of $310,000, a median of 35 days on market for recently sold homes, and 11 active listings. An individual home's value depends on its condition, street, build year, and timing, but at that price level a missed septic, well, or foundation issue can be a major hit to your finances. In my experience, that's a reason to narrow your contingency strategically rather than erase it.

Western Massachusetts

Massachusetts uses different purchase documents, and septic and well rules there aren't the same as Connecticut's. Before you write an offer on an older home across the state line, I'd review the current Massachusetts purchase-and-sale documents and your town's requirements with you rather than assume anything from the Connecticut forms.

South Florida

The risk list shifts. Flood history and flood zone, roof age and condition, drainage, moisture intrusion, mold, electrical equipment, and hurricane-related damage all call for qualified specialists. If a seawall or dock is part of the property, that needs its own evaluation. I work with buyers in all three markets, so a move within Connecticut or a relocation south gets local insight rather than a generic checklist.

If you'd like to see how other buyers describe working with me, you can read my reviews on Google and Zillow.

FAQ

Should I waive the home inspection to make my Connecticut offer stronger?

I wouldn't waive it outright. A waiver can help your offer, but it also removes your protection against hidden defects. A narrower contingency that keeps structure, major systems, and specialist tests can often compete well without leaving you exposed.

Can I keep an inspection contingency but limit it to major structural or safety problems?

Yes, that's a negotiable structure. The Connecticut model agreement and addenda support separately identified research categories, so the contract can preserve structural, roof, mechanical, environmental, septic, well, or radon review. Your actual rights depend on the wording you and the seller agree to, so have it reviewed before you sign.

Do I need a separate well-water test or well-yield test in Connecticut?

If the home has a private well, I recommend it. A general inspection does not establish that the water is potable or that the well delivers enough water. A well-flow or yield test and laboratory water testing answer those two separate questions.

Should I get a radon test if the seller already disclosed a prior test?

A prior test is useful, but it only reflects conditions on the day it was done. The seller's disclosure form asks whether a test was performed and directs the seller to attach the report if available. Whether you want a fresh test depends on how old the report is and your comfort level, and I can help you decide.

Who should inspect a suspected pyrrhotite or deteriorating concrete foundation?

A licensed professional engineer who is a structural engineer. That's the specialist the Connecticut Residential Property Condition Report recommends for a potentially affected concrete foundation. A general home inspector can flag cracking or staining, but they aren't the final evaluator.

The bottom line on a home inspection in Connecticut is simple: protect yourself where the problems are expensive and hidden, and stay flexible everywhere else. I'll help you build an offer that does both, whether you're buying in Connecticut, Western Massachusetts, or South Florida. Schedule a consultation with me and we'll look at your target home and decide which inspection terms make sense before you submit.

About Lori Gabriel

Lori Gabriel is a Broker (ABR, CRS) and leader of Team Gabriel, serving buyers and sellers across North Central Connecticut, Western Massachusetts, and South Florida.

Coldwell Banker Realty · 860-926-5101

Equal Housing Opportunity. Team Gabriel at Coldwell Banker Realty, regulated by the Connecticut Real Estate Commission. This article is general information, not legal, tax, or financial advice; confirm your own numbers and contract terms with your closing agent, tax advisor, or lender. By providing contact info, visitors consent to telemarketing/automated calls and texts from teamgabriel.net; message and data rates may apply.
Oct. 21, 2026

Confused by Home Price Headlines? Here’s Why.

Whether you own a house already or you’re looking to buy one, you probably care about home prices. But it’s not always easy to figure out what’s really happening right now, especially if you look at the headlines.

One says home prices are falling. The next says they’re still climbing.

So, which one’s right? It comes down to where you live.

What’s Really Going on with Asking Prices

Part of the confusion out there may be based on what’s happening to asking prices and how the media is talking about it. They’re calling attention to how asking prices are falling, but don’t give the full context or say that seasonality is at play. So here it is.

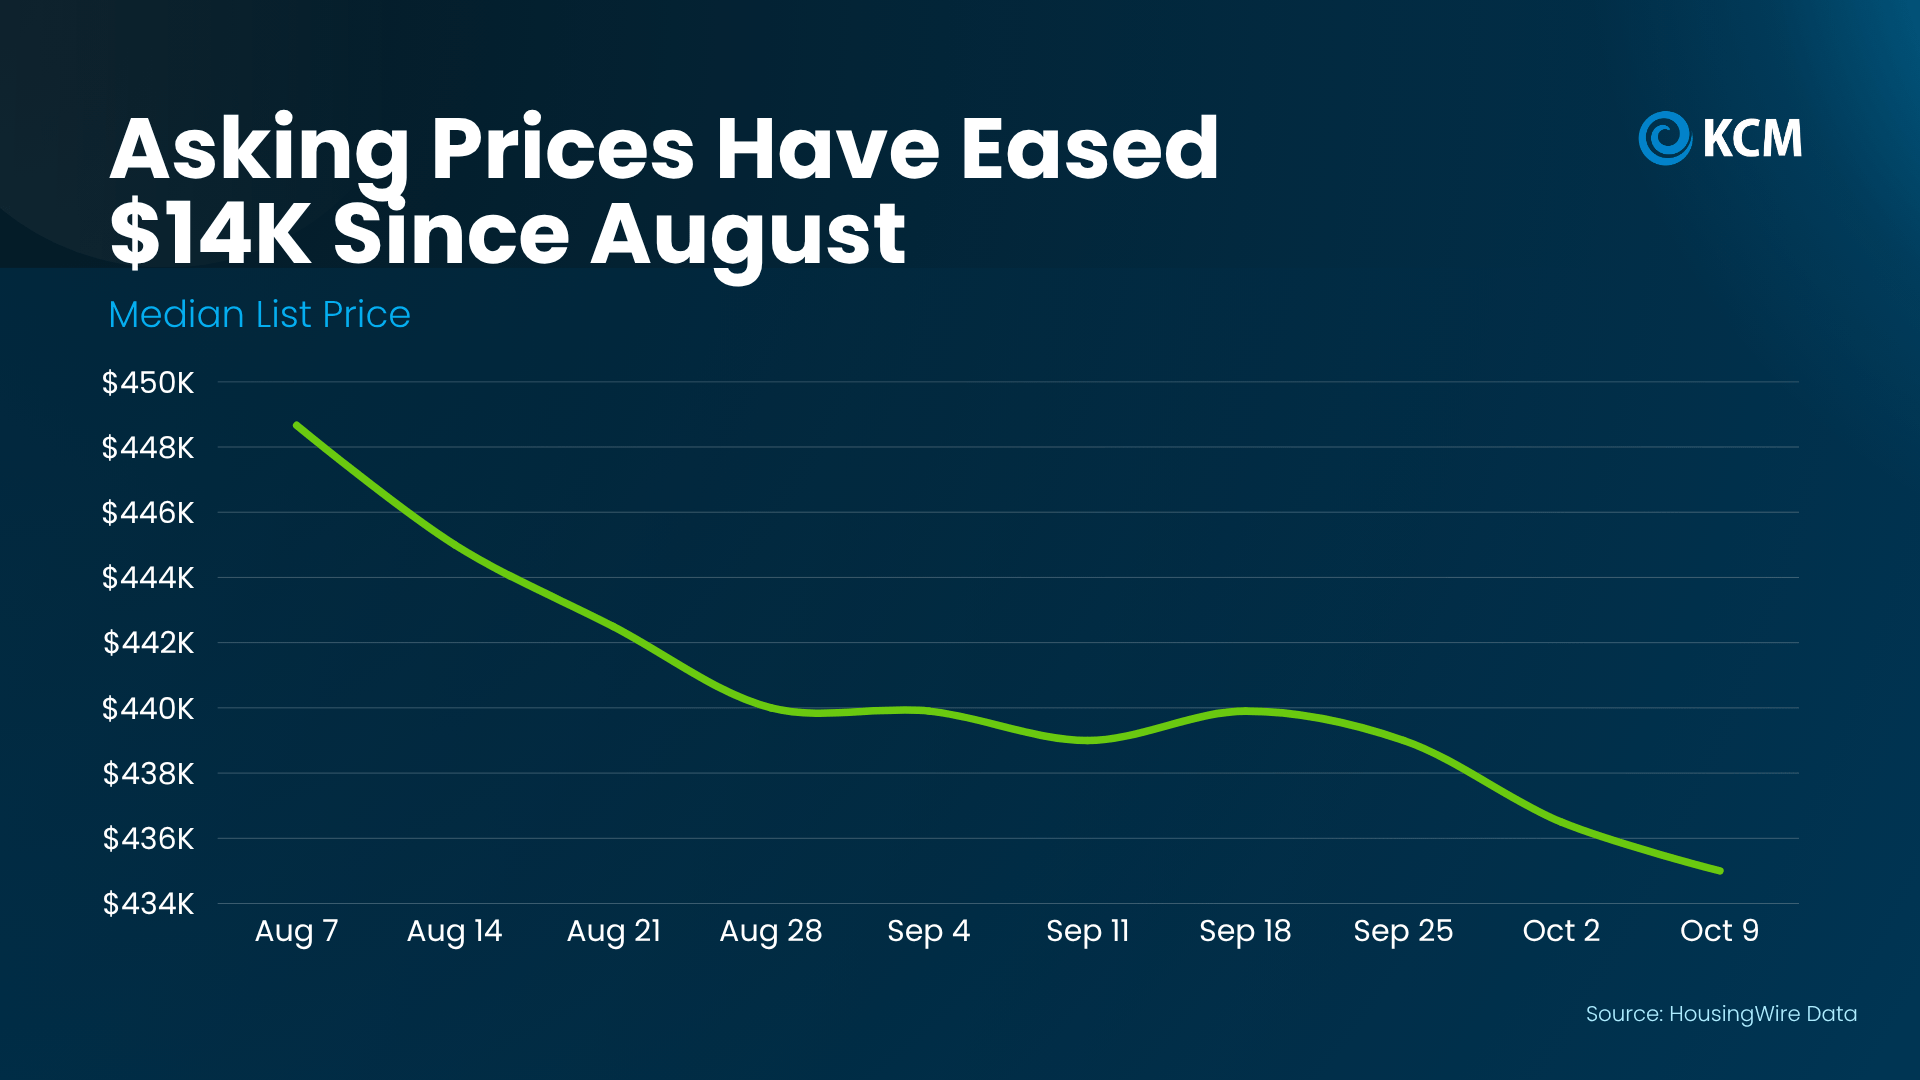
Right now, there are more homes on the market than at any other time since November 2019. And with mortgage rates rising since the spring, those homes are taking a little longer to sell. One way to help a home sell quickly in that environment is to have a lower asking price.

According to HousingWire Data, the median asking price is down from $449k in early August to $435k just 2 months later (see graph below):

That’s a dip of about 3%, and a lot of it is normal for this time of year.

Asking prices cool off every fall once the busy summer season wraps up. With fewer buyers this time of year, sellers price a bit more competitively. Today’s rates play a role too, since sellers are pricing to match what buyers can afford right now. And that’s a good thing. Smart pricing helps homes sell.

Just keep in mind, that’s a national list price. It doesn’t show what homes near you are actually selling for. So before you react to a headline, ask a local agent what’s really happening in your area.

Where You Live Changes Everything

Realtor.com explains:

“While national headlines might suggest a buyer’s market is taking hold, the reality on the ground depends heavily on where and what you’re trying to buy. Local trends can diverge sharply from national averages, especially when you factor in price range, property type, and post-pandemic market dynamics.”

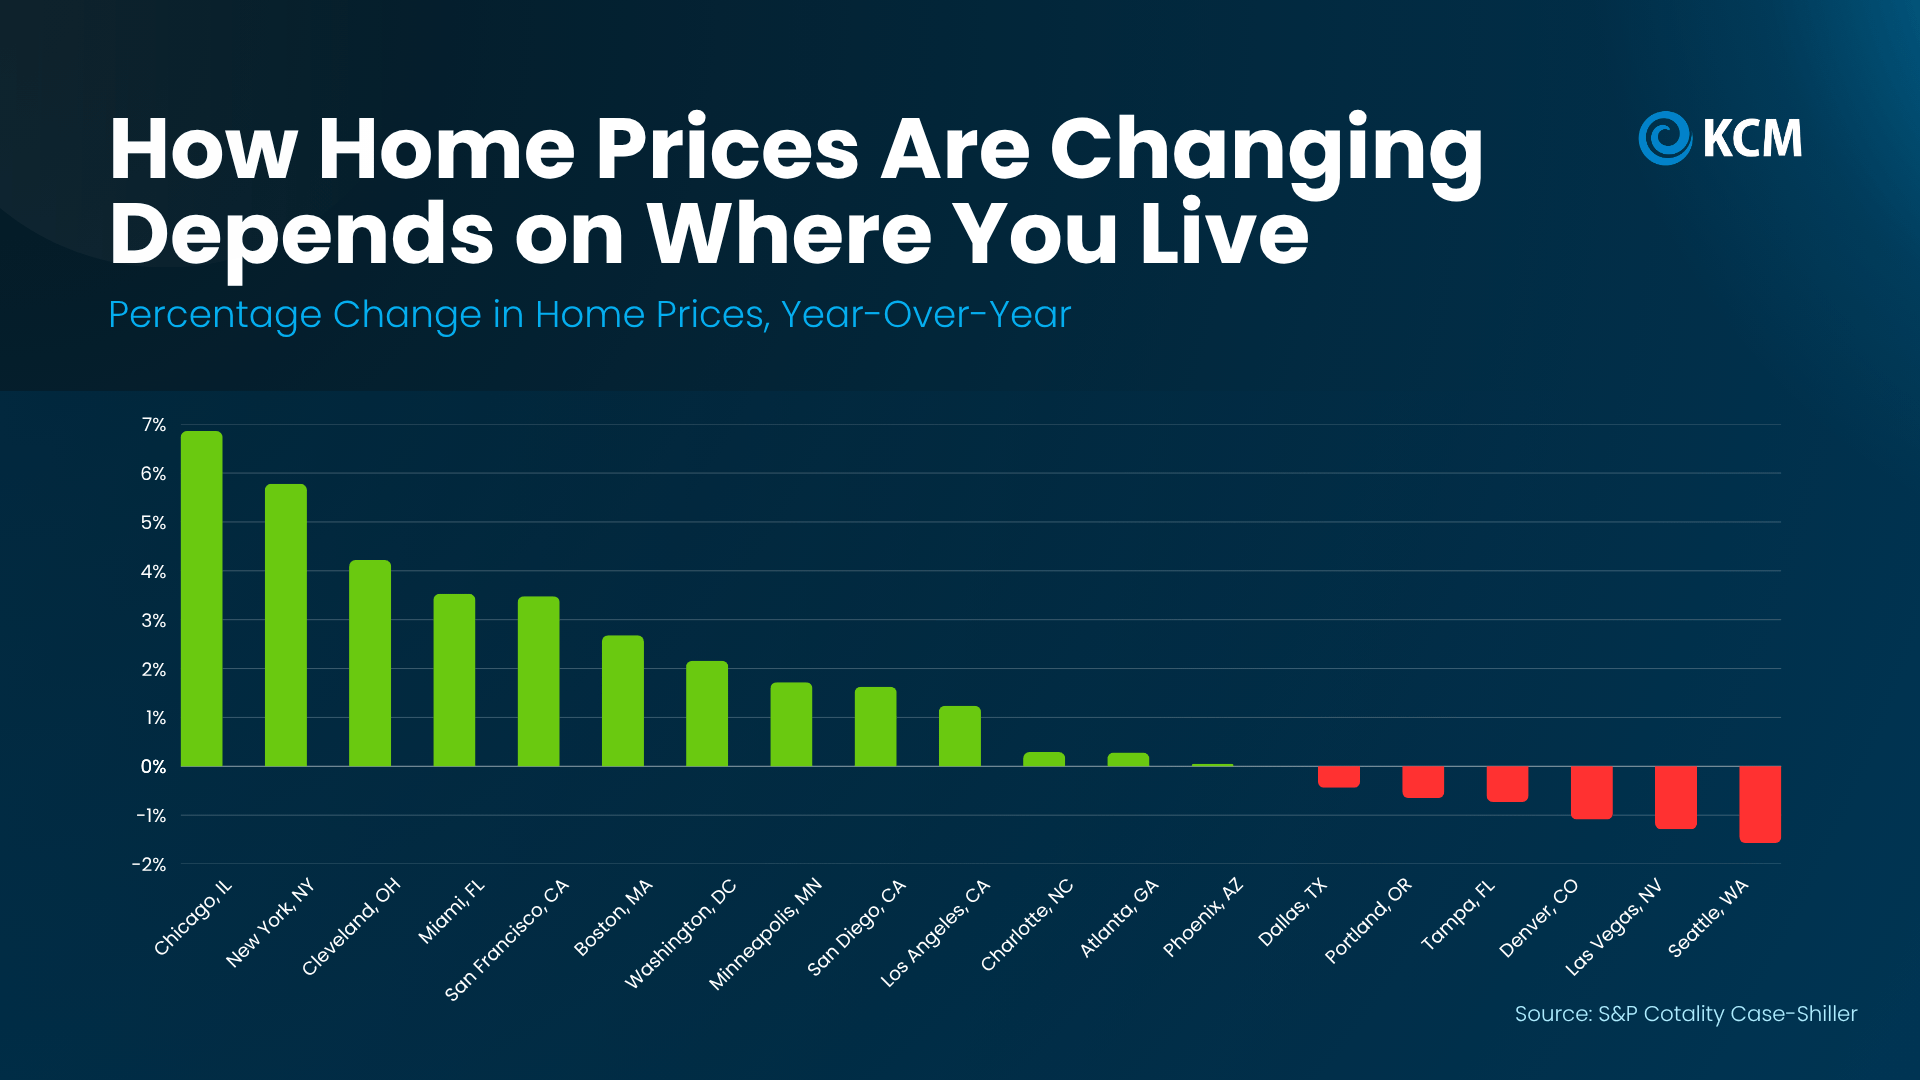
The latest numbers from S&P Cotality Case-Shiller Index show how true that is. Over the past year, sales prices in Chicago rose almost 7%. In Seattle, they dipped about 1.6%. That’s a gap of nearly 9 percentage points between two major cities (see graph below):

That gap changes your game plan. Selling in New York, where prices are up almost 6%? You may not need to cut your price. Buying in Denver or Las Vegas? You may have more room to negotiate.

Why You Don’t Need To Worry About a Crash

Just in case you’re seeing those slight declines in some markets and worried it means a bigger crash is coming, here’s what you need to remember. Even in the major metros where prices are down, the declines are 2% or less. That’s a long way from a crash like 2008. And if you look back at the graph above, there are more cities in the green than in the red.

And over time, home values have a strong track record. The Federal Housing Finance Agency (FHFA) says national prices have grown year-over-year every quarter since 2012. Go back further, and a $100k home bought in 1991 would be worth about $436k today, even with the 2008 crash factored in (see graph below):

So, this short-term dip probably won’t stick around. The small declines we’re seeing now are in markets that overheated during the pandemic. As a whole, the market is headed back to normal – and normal means prices should rise over time.

In Conclusion

National headlines can’t tell you what your home is worth or how much room you have to negotiate. Local data can. If you’re thinking about buying or selling, let’s look at how prices are moving in your area, so you can set your price or make your offer with confidence.

Posted in Buyers, Sellers
Oct. 21, 2026

Impact on Local Homebuyers From Bradley Airport Expansion

By Lori Gabriel · Oct 21, 2026

Bradley's expansion affects buyers unevenly. The airport has added terminal capacity and is building 1,500+ parking spaces, which helps frequent travelers, but no verified study shows a blanket change in home values. Results depend on a property's distance from the terminal, its access roads, and any regularly used flight paths.

Impact on Local Homebuyers From Bradley Airport Expansion

What is the impact on local homebuyers from the Bradley Airport expansion?

The impact on local homebuyers from Bradley International Airport's expansion is real but uneven. The airport has finished a major terminal program and is adding more than 1,500 parking spaces, which improves access for frequent travelers. No verified study shows a blanket change in home values, though, so what you gain or give up depends on the specific property: its distance from the terminal, its access roads, and whether it sits under a regularly used flight path.

Key Takeaways

  • East Windsor's median sale price was $310,000 in recent local market data (trailing 90 days), with 24 homes sold, a median of 34 days on market for those sold homes, and 11 active listings.
  • Bradley's parking expansion on Schoephoester Road covers about 14 acres, adds more than 1,500 spaces, and raises capacity by roughly 20%, with completion expected in winter 2026-27 or spring 2027.
  • Passenger traffic fell 4.2% in the first half of 2026 (about 3.15 million versus 3.29 million), so the expansion adds capacity and does not prove growth.
  • No current source documents a town-level or parcel-level effect of the expansion on residential values, so treat any promise of appreciation near the airport as unverified.
  • The practical question for a buyer is trade-offs: shorter access to flights versus aircraft noise, nighttime operations, and construction or road traffic near the property.

What has actually changed at Bradley Airport?

Bradley has completed more than $250 million in recent capital projects and is now building a large parking expansion. That is the verified part of the story, and it's worth separating from the speculation about what it does to prices.

Terminal and security work

The Connecticut Airport Authority reports that more than $250 million in recently completed projects included a new concourse, expanded TSA screening, new passenger exit lanes, and improved passenger circulation. The terminal work added three gates and modernized baggage screening with an integrated inspection facility, and AviationPros reported the project as completed in February 2026. In September 2026, Bradley also added two TSA lines to its main security checkpoint.

The airport's official planning page lists further medium-term projects for the 2023-2027 period, including apron expansions, taxiway and runway-related work, remote-parking expansion, an inline baggage building, and more gate and hold-room space. Check that page for the timing of any individual project before you assume it's done or still coming.

The Schoephoester Road parking project

The parking expansion is the piece closest to the ground for neighbors. It enlarges a surface lot on Schoephoester Road by about 14 acres and adds more than 1,500 spaces, roughly a 20% increase in capacity. The Hartford Courant reported in August 2026 that completion is expected in winter 2026-27 or spring 2027, depending on the project description.

For a buyer, that means construction activity and added vehicle movement along that corridor while the work is underway. Once it's finished, it should be easier for you to park and fly if you travel often.

Is traffic actually growing?

Not in the first half of 2026. The same Courant report shows Bradley handled about 3.15 million passenger movements from January through June 2026, down 4.2% from about 3.29 million in the same months of 2025. Nonstop service stood at 43 destinations in August 2026, down from 46 a year earlier after Avelo Airlines left the market.

The parking project is a response to crowding at peak times. NBC Connecticut reported that Bradley's existing lots frequently fill during busy travel periods, and officials describe the added spaces as room for current demand and future routes. That's capacity planning, and it shouldn't be read as proof that the airport is booming. I walk my clients through this distinction because it keeps expectations realistic.

I cover the Windsor Locks angle in more detail in my post on Bradley Airport expansion and Windsor Locks real estate, and the wider ripple in how the $250 million expansion affects Windsor.

Will the expansion raise home values in Windsor Locks and nearby towns?

Nobody can honestly promise that. The available sources document airport investment, parking capacity, terminal upgrades, and passenger activity, but none provides a town-level or parcel-level analysis showing the expansion has raised or lowered residential values.

That's why I frame the impact on local homebuyers as a set of trade-offs rather than a price forecast. Windsor Locks is the host town, so the most direct effects are likely to be highly localized, not spread evenly across North Central Connecticut. A home close to the terminal, a home near a major access road, and a home under an established aircraft route are three different propositions.

What the local numbers say

Recent local market data for East Windsor, covering roughly the trailing 90 days as of October 2026, shows a median sale price of $310,000. In that stretch, 24 homes sold, the median time on market for those sold homes was 34 days, and there were 11 active listings. Those are area-level figures. An individual home's value depends on its condition, street, build year, and timing.

A statewide report also noted 2,335 closed sales across Connecticut and agents describing a market that has been slowing faster than normal. That's a statewide number, so don't read it as a Windsor Locks figure. It does tell you that buyers aren't operating in a frenzy right now, which gives you room to do careful due diligence.

For context, here is how several nearby towns in my coverage area compare. The airport is not the reason for the differences in this table, and I'm showing it so you can calibrate price levels, not to rank areas.

Source: aggregated public listing data, trailing 90 days, as of October 2026.
Area Median Sale Price Median Days on Market
Enfield $354,250 41
South Windsor $445,306 26
Suffield $502,500 50

The days-on-market column counts homes that sold, so it reflects how long those listings were on the market before closing.

How to test the airport's effect on a specific home

Look at what comparable homes have actually sold for, not what they're listed at. The best evidence of airport exposure is a pair of similar homes, one nearer the terminal or a flight path and one farther away, and the prices each one closed at. That kind of comparison is exactly what a local market analysis does, and your numbers will depend on the exact property.

How should I evaluate a home near Bradley Airport before I buy?

Evaluate the property itself, not the airport's headlines. The checks below are practical research steps and won't predict a numerical effect on value.

  1. Visit at different times of day. Go on a weekday morning, an evening, and a weekend. Listen for aircraft and note how often they pass.
  2. Check airport and roadway maps. Find out whether the property is near the terminal, near a main access road, or near the Schoephoester Road project area.
  3. Ask whether the home lies under a regularly used flight path. Ask the seller and the neighbors, and confirm what you hear on your visits.
  4. Compare similar homes with different exposure. Pull sold comparables for homes that differ mainly in how close they are to the airport or its roads.
  5. Test the drive. Run the route to the terminal at the hours you'd actually travel, since parking-lot and road conditions change with the peak periods the airport has described.
  6. Talk to your lender. Confirm how your specific property will be handled in underwriting and appraisal before you write an offer.

Is it more convenient to live near Bradley if you fly often?

It can be. Living close shortens your trip to the terminal and can reduce how often you'd consider flying out of Boston Logan or a New York-area airport. The cost of that convenience is exposure to aircraft noise, possible nighttime operations, and road traffic. If you fly weekly, the trade may be worth it. If you fly twice a year, you may be paying for convenience you rarely use.

What about Western Massachusetts buyers?

Communities in Hampden County, such as Longmeadow, East Longmeadow, Agawam, and Springfield, may offer good access to Bradley without the same direct airport-land-use exposure as Windsor Locks-area neighborhoods. I wouldn't assume identical results, though. Compare actual drive times and check each property's location before you decide.

Relocating from out of state?

Because I work in North Central Connecticut and Western Massachusetts (and with South Florida buyers moving north), I often hear from relocating clients who want to know how far Bradley sits from the towns they're considering. New routes could make airport access more appealing over time, but that's an expectation, not a verified trend, especially with 43 destinations in August 2026 versus 46 a year earlier. Choose a home for how you'll live in it today.

If you'd like to see what past clients say about working with me, you can read my reviews on Google and Zillow.

FAQ

Will Bradley's expansion raise home values in Windsor Locks and nearby towns?

No verified study shows that it has raised or lowered residential values. The documented changes are terminal upgrades, new TSA lines, and added parking, and the effect on any one home depends on its exposure to aircraft, roads, and the airport itself. A comparison of recent sales for similar homes is the best way to see it for a specific property.

Which neighborhoods are most affected by Bradley Airport noise?

Noise depends on the individual property, not on a town-wide label. The homes most likely to notice aircraft are those near the terminal or beneath regularly used flight paths. Visit at different times of day, review airport maps, and ask whether the home sits under an established route.

How far can I live from Bradley and still have a practical commute?

It depends on your route and the hours you travel, so test the drive yourself. Towns across North Central Connecticut and parts of Western Massachusetts offer access to Bradley, and the right distance is the one that fits your travel schedule and your tolerance for peak-period traffic.

Does buying near Bradley create resale or financing risks?

There is no verified blanket resale or financing penalty, but individual homes can differ in appeal depending on noise and road exposure. Talk to your lender early, and compare sold prices for similar homes with different levels of airport exposure to see how the market treats them.

Will the parking and terminal projects increase traffic around Windsor Locks and Suffield?

The Schoephoester Road parking project will bring construction activity and added vehicle movement to that corridor while it's underway, with completion expected in winter 2026-27 or spring 2027. After that, the added parking is meant to ease crowding at the airport. How much traffic you'd notice depends on how close the home is to the access roads, which is worth checking in person.

Where to go from here

The expansion's impact on local homebuyers comes down to trade-offs at the property level: easier airport access against noise, traffic, and construction near the corridor. If you're weighing homes in Windsor Locks, Suffield, East Windsor, Enfield, or across the river in Hampden County, I'll pull the sold comparables, map the exposure, and run the drive times with you. Schedule a consultation with me and we'll look at the specific homes you're considering.

About Lori Gabriel

Lori Gabriel is a Broker (ABR, CRS) and leader of Team Gabriel, serving buyers and sellers across North Central Connecticut, Western Massachusetts, and South Florida.

Coldwell Banker Realty · 860-926-5101

Equal Housing Opportunity. Team Gabriel at Coldwell Banker Realty, regulated by the Connecticut Real Estate Commission. This article is general information, not legal, tax, or financial advice; confirm your own numbers with your closing agent, tax advisor, or lender. By providing contact info, visitors consent to telemarketing/automated calls and texts from teamgabriel.net; message and data rates may apply.
Oct. 20, 2026

Would your home sell this fall in North Central CT & Western MA?

Posted in Sellers, Selling a Home
Oct. 19, 2026

North Central Connecticut Buying and Selling Process

By Lori Gabriel·Oct 19, 2026

Buying or selling in North Central Connecticut starts with local sold data, since recent medians run from $310,000 in East Windsor to $610,000 in Somers. Bradley Airport's projects are real, but they don't guarantee a price bump for any one home. Your steps are pricing or pre-approval, inspections, and a closing agent.

North Central Connecticut Buying and Selling Process

What should you expect when buying or selling in North Central Connecticut?

Expect a market that varies town by town: recent sold-home medians in North Central Connecticut range from $310,000 in East Windsor to $610,000 in Somers, and homes took roughly 34 to 61 days to sell depending on the town. Bradley International Airport's improvements add context to local valuation, but they don't guarantee a price increase for any individual property. Your process comes down to accurate pricing or a solid pre-approval, an inspection and appraisal window, and a closing handled by a closing agent.

Key Takeaways

  • East Windsor's median sale price was $310,000 across 21 recent sales, and those homes had a median of 34 days on market.
  • Enfield's median days on market for sold homes was 61, while Somers (60 days) posted the highest median sale price of the five towns at $610,000.
  • Bradley's recent capital improvements exceeded $250 million, but airport expansion alone is not evidence that your home's value will rise.
  • In Connecticut, the grantor (the seller) or an authorized representative files the conveyance tax return, while the allocation of closing expenses can be negotiated in the contract.
  • Homes near the airport should be valued with property-level factors like flight-path position, road access, and noise exposure, not a town-wide average.

What are homes selling for across North Central Connecticut?

Recent local market data shows sold-home medians from $310,000 to $610,000 depending on the town. That spread is why a single regional number is never enough to price a home or write an offer.

Here's the most recent snapshot I work from. It covers the trailing 90 days as of October 2026, and the days-on-market column reflects homes that actually sold.

Source: aggregated public listing data, trailing 90 days, as of October 2026.
Area Median Sale Price Median Days on Market
East Windsor $310,000 34
Ellington $417,500 48
Enfield $347,000 61
Somers $610,000 60
Suffield $496,250 53

These are area-level medians. An individual home's value depends on condition, street, build year, and timing, and a median can shift quickly when only a few dozen homes sell in a quarter.

East Windsor shows how thin the data can be. Recent local market data shows 11 active listings, 7 new listings in the last 30 days, and 21 homes sold over roughly 90 days. With inventory that tight, one well-priced listing or one overpriced one noticeably changes the picture.

What this means if you're selling

Before you choose a list price, look at what homes have actually closed for on your type of property, not what neighbors are asking. Asking prices are opinions. Sold prices are what buyers and appraisers respond to.

A comparative market analysis built on true comparable sales is where I start with every seller. If you want the pricing logic in more depth, I break it down in pricing a North Central Connecticut home in a split market. For timing context, see whether it's a good time to sell in North Central CT.

What this means if you're buying

Use the table to calibrate expectations, then narrow to the specific streets and property types you'd actually consider. A buyer comfortable in the $300,000s is looking at a very different search in Enfield or East Windsor than in Somers or Suffield.

Homes that sold in roughly a month tell you where the competition was tighter. Where the median ran closer to two months, buyers generally had more room to negotiate and inspect without as much pressure. Your own offer strategy should still come from the specific house and its comparable sales.

How does Bradley International Airport affect home values in North Central Connecticut?

Bradley's investments improve the airport's capacity and convenience, but they don't establish a guaranteed effect on any individual home's price. For homes in the corridor, the value question is property-specific.

The documented projects are substantial. The Connecticut Airport Authority has reported that the terminal expansion is substantially complete, including new exit corridors and improved passenger circulation. CT Insider reported that recent capital improvements topped $250 million, including a new concourse, additional exit lanes, expanded meet-and-greet areas, and a larger TSA checkpoint.

Parking is the next piece. As reported in August 2026, the Surface Lot 3 project adds more than 1,500 spaces on about 14 acres near Schoephoester Road, raising airport-operated parking capacity by roughly 20%. Completion was expected in winter 2026-2027, so confirm the final status with Bradley or the Connecticut Airport Authority before treating it as done.

Which property-level factors matter near the airport?

Bradley sits in Windsor Locks, and its pull reaches Windsor, Suffield, and surrounding Hartford County communities. Whether that helps or hurts a particular home depends on details a town average can't capture:

  • Flight-path position and aircraft noise at the specific address
  • Road and highway access and how traffic patterns affect the street
  • Rental demand and the pool of buyers who value airport accessibility
  • Zoning and nearby commercial activity versus purely residential surroundings

If you're selling near the airport, document your improvements, describe access and transportation advantages accurately, and disclose material property conditions as your transaction documents and the law require. Never market the expansion as a promise of appreciation. If you're buying, visit at different times of day and judge the street itself. Every situation is different, and a local market analysis is the only reliable way to put a number on it.

What does the buying and selling process look like in North Central Connecticut?

The process follows the same general sequence in every town: prepare, price or search, negotiate, complete inspections and financing steps, then close with a closing agent. Where the timeline stretches or shrinks depends on the property and the local market.

The buyer's path

  1. Get pre-approved with a lender so your offer carries weight and your budget is real.
  2. Narrow your search by commute, property type, and the market data above.
  3. Make an offer grounded in recent comparable sales, not the asking price alone.
  4. Complete your inspections and appraisal. Inspection contingencies typically give you a window to negotiate repairs or walk away, and I'll explain exactly how yours works before you write an offer.
  5. Close with your closing agent, who handles settlement and the transfer of funds.

Wondering how long the whole thing takes? I cover it in how long it takes to buy a home in North Central Connecticut.

The seller's path

  1. Review comparable sales and set a price strategy before you list.
  2. Prepare the home and invest in strong visuals. Here's my take on whether professional photos are worth it in North Central CT.
  3. List and show, then review offers on price, financing strength, and contingencies.
  4. Work through the buyer's inspection and appraisal without losing momentum.
  5. Close with the closing agent.

Broker fees are fully negotiable and not set by law. Any compensation you choose to offer a buyer's agent is optional and separately negotiable too. The place to settle both is your listing agreement, and I'm glad to walk through it with you. For a breakdown of the cost categories, read the cost to sell a house in North Central CT, then let's build your personal numbers together.

Zooming out, I also cover the bigger picture in buying and selling real estate across Central Connecticut.

Want to see what past clients say about working with Team Gabriel? Read my reviews on Google and Zillow.

FAQ

What are homes currently selling for in North Central Connecticut?

Recent sold-home medians run from $310,000 in East Windsor to $610,000 in Somers, with Enfield at $347,000, Ellington at $417,500, and Suffield at $496,250. These are trailing 90-day, area-level figures as of October 2026, so your home's value depends on its condition, street, and timing.

How long does it take to buy or sell a home near Bradley International Airport?

Recent sold homes in the towns above had median days on market between 34 and 61, but that measures listing time, not your full timeline. Buying also includes your search, inspections, financing, and closing, so your pace depends on the property and your preparation.

Does Bradley International Airport expansion increase nearby home values?

Not automatically. The terminal, concourse, and parking projects improve the airport itself, but a home's value near Bradley still turns on noise exposure, flight-path position, road access, and buyer demand. A comparable-sales analysis of your specific property is the only way to judge it.

Should I compare North Central Connecticut with Western Massachusetts before buying?

Yes, especially if your commute or budget is flexible. Because Team Gabriel works in both markets, I can compare commute time, property taxes, insurance, and resale demand side by side. Those are decision factors, so I'd run them against the specific homes you're considering.

How do Connecticut's real estate conveyance taxes affect a home sale?

The Connecticut Department of Revenue Services identifies the grantor (the seller) or an authorized representative as the party that files the conveyance tax return, Form OP-236. Who ultimately bears closing expenses can be addressed in the purchase contract, so confirm the details with your closing agent.

Whether you're buying your next home or preparing to list, the right starting point is local sold data and a clear read on your specific property. That's what Team Gabriel brings to every client in the region. Schedule a consultation and we'll map out your next step together.

About Lori Gabriel

Lori Gabriel is a Broker (ABR, CRS) and leader of Team Gabriel, serving buyers and sellers across North Central Connecticut, Western Massachusetts, and South Florida.

Coldwell Banker Realty · 860-926-5101

Equal Housing Opportunity. Team Gabriel at Coldwell Banker Realty, regulated by the Connecticut Real Estate Commission. This article is general information, not legal, tax, or financial advice; confirm your own numbers with your closing agent, tax advisor, or lender. By providing contact info, visitors consent to telemarketing/automated calls and texts from teamgabriel.net; message and data rates may apply.
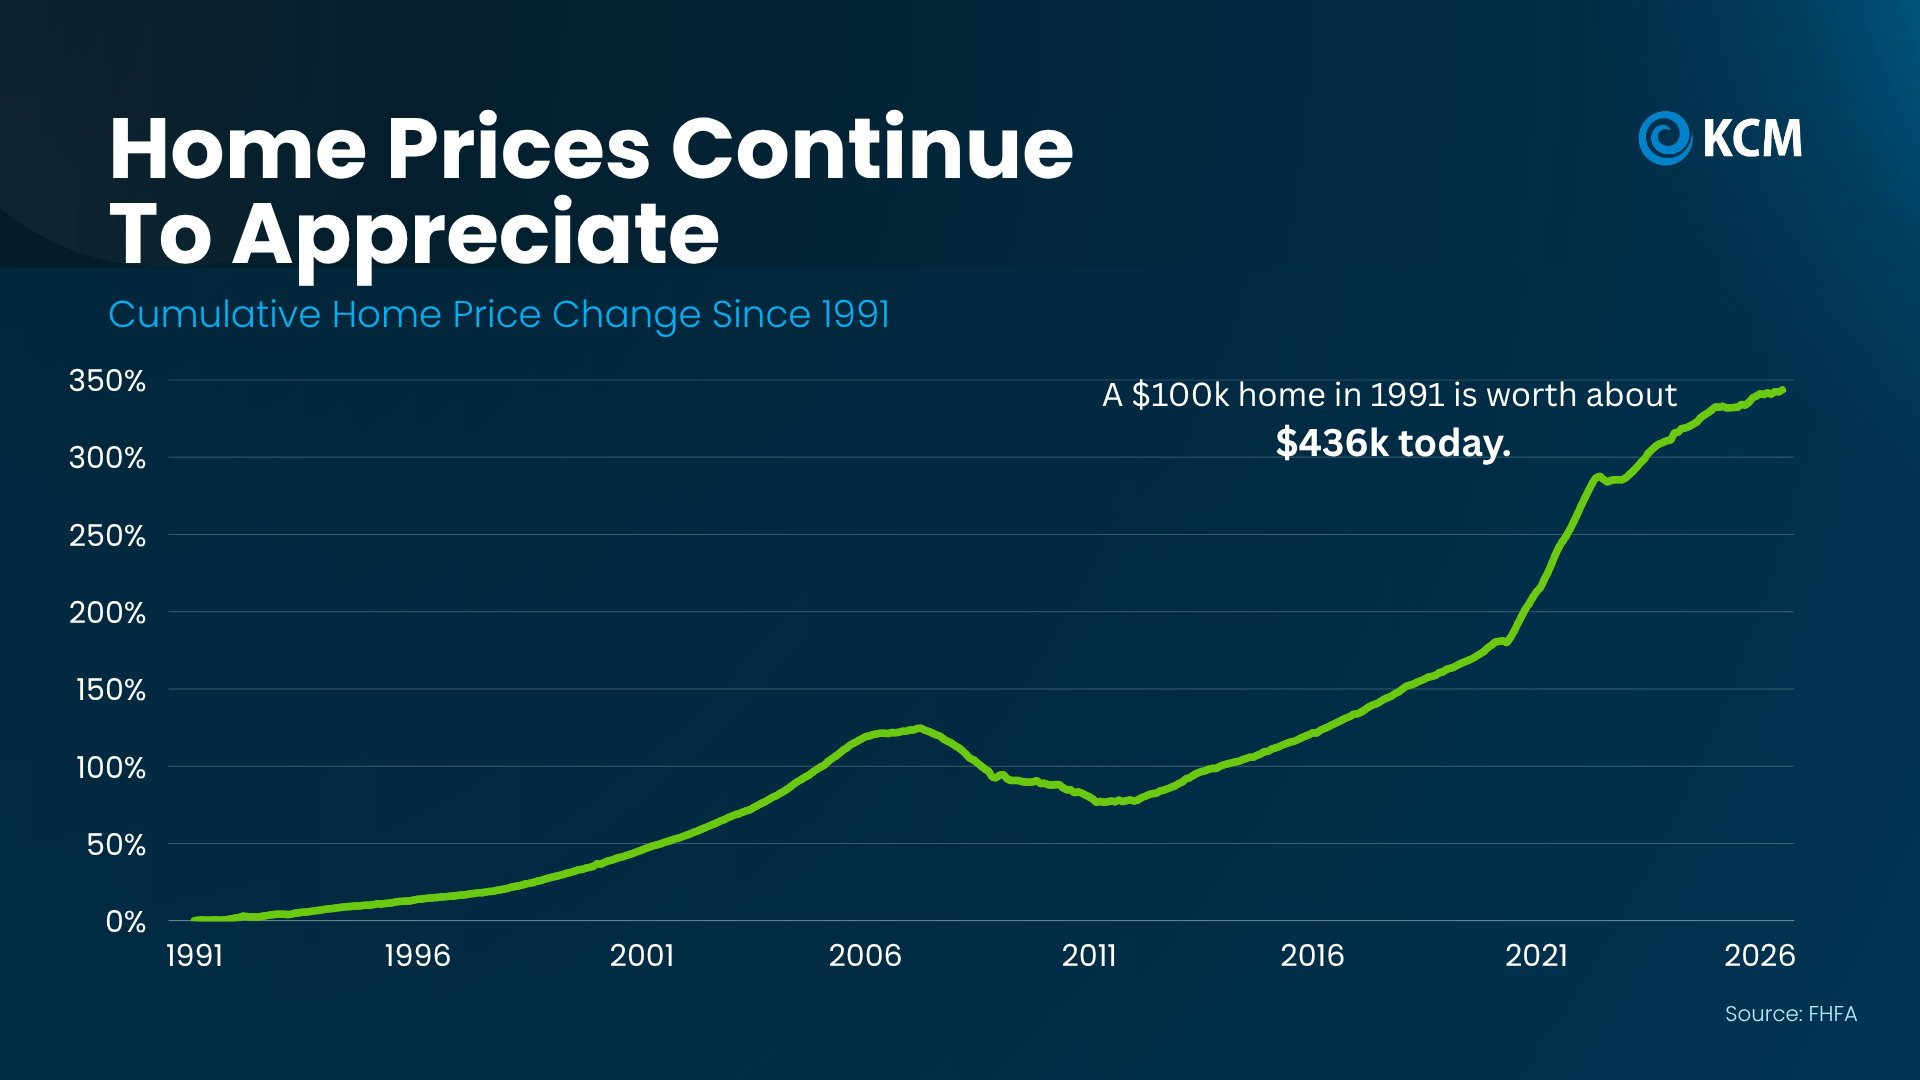
Oct. 16, 2026

The Biggest Credit Hurdle for Renters Who Want To Buy

What's the biggest payment you make every month? If you’re a renter, it's probably your rent. 
But did you know that you can pay your rent on time, every time, for years, and it may never show up in your credit history? It's pretty frustrating, especially if you'd like to buy a home someday and you’re trying to build your credit.

The good thing is that’s changing right now. Here’s what you need to know and why it could open a door you thought was closed.

The Problem for Would-Be Buyers

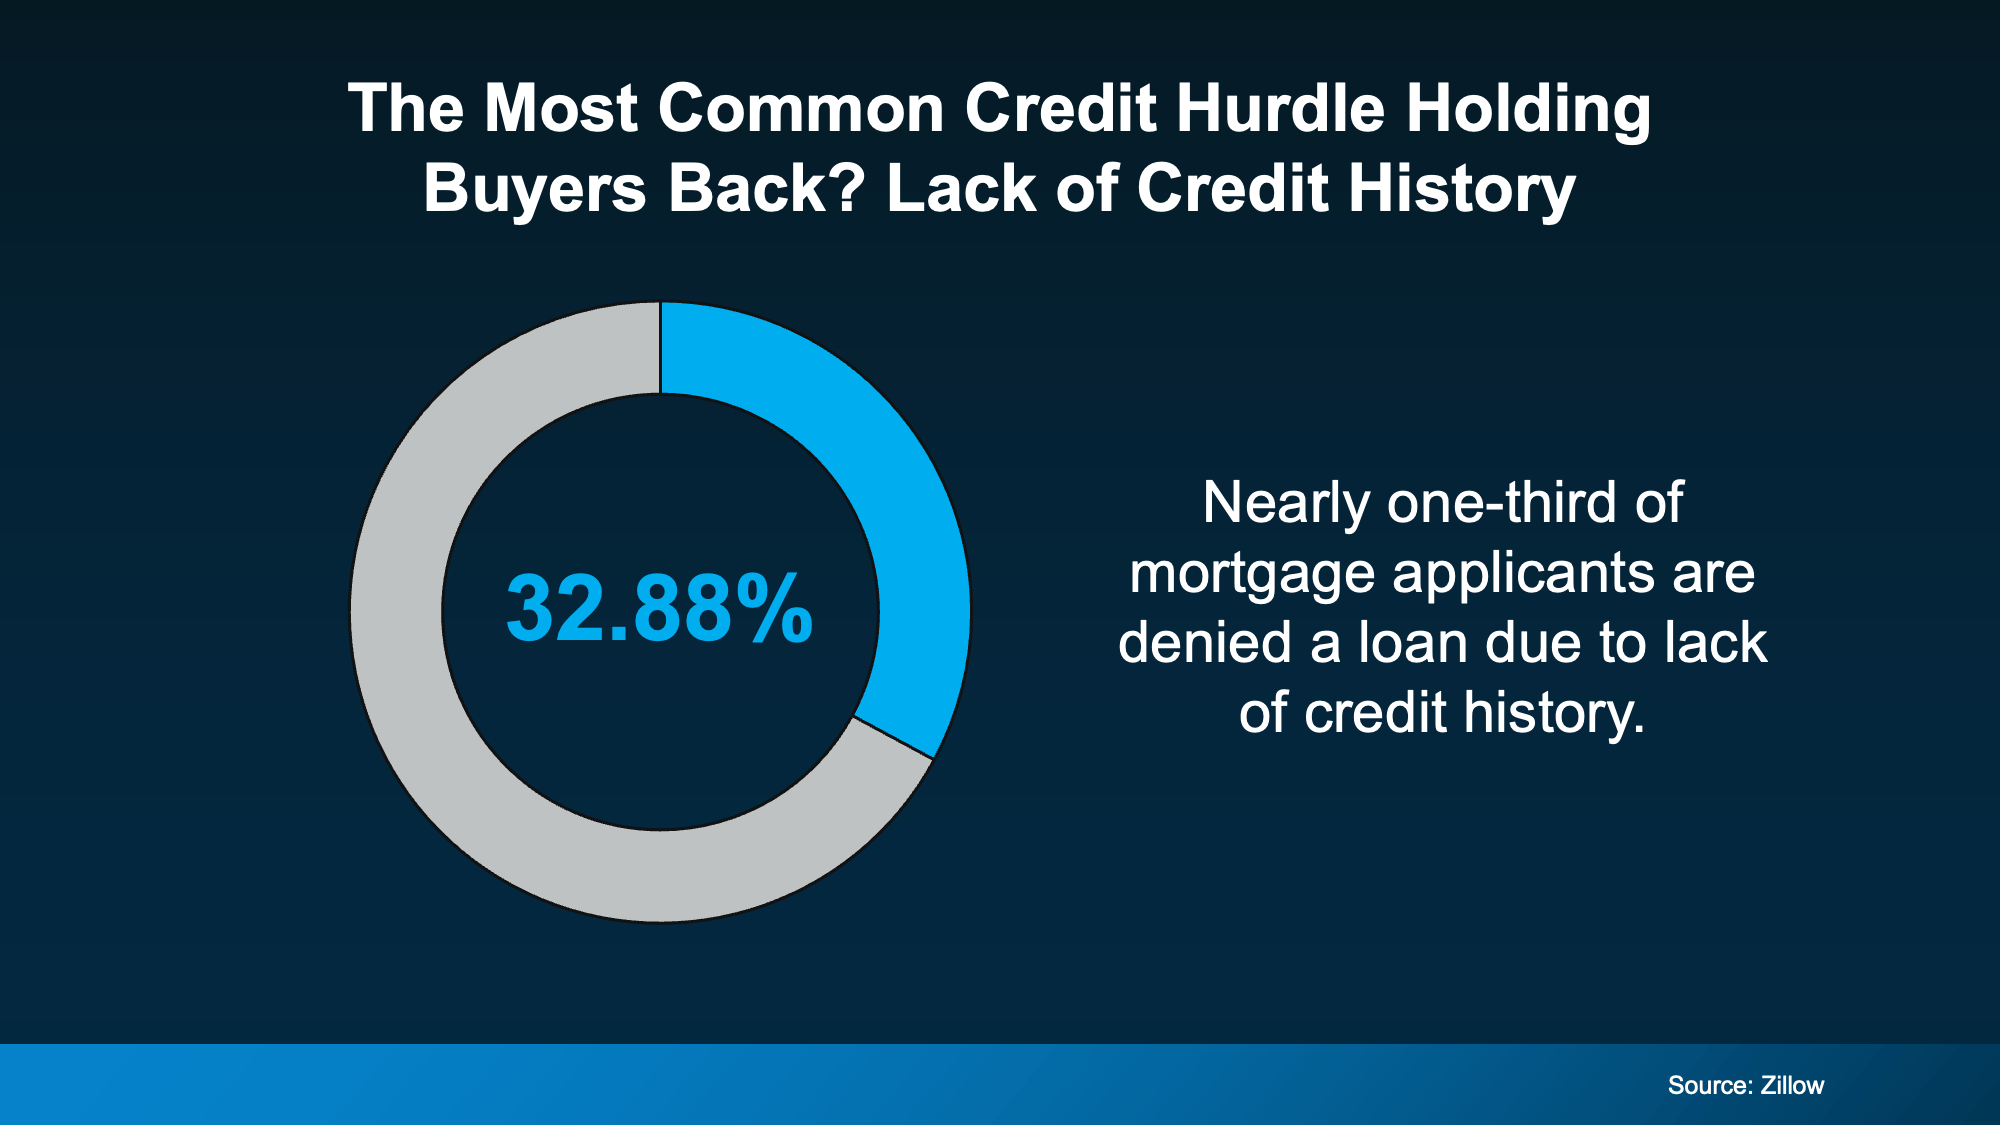
You’re not the only one frustrated. According to Zillow, nearly a third of applicants (32.88%) get denied a mortgage due to insufficient credit history - not missed payments or too much debt. Just not enough credit history for a lender to say "yes."

It’s the most common hurdle would-be buyers have. As Zillow explains:

“Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history, making it the most common reason for a denial.”

But there’s finally a way in now that how credit gets measured is changing.

The Good News: Credit Is Getting Broader

As Michael Sherman, General Manager and Senior VP at Zillow Rentals, explains:

"Affordability is the headline in housing right now, and access to financing is a very important part of the story. Credit history is a barrier standing in the way of too many potential buyers. Rent reporting is a direct way to address that.”

Here’s what Sherman is talking about. New credit models are emerging that take on-time rent and some utility payments into consideration to help renters get credit for the bills they already pay.

VantageScore is one company with a new credit model that has been approved for use by the Federal Housing Finance Agency (FHFA). And that roll out could have a big impact on renters like you.

A recent study by VantageScore found that nearly 4 million U.S. renters could finally become eligible for a mortgage if their on-time rent payments were counted as part of their credit history. Now, this isn’t a guarantee that it will suddenly count for every would-be buyer, but it does crack open the door.

Here’s the catch though, you still have to walk through it.

Counting Rental Payment History Is Not Automatic

There are more options available to build credit, but you have to be proactive. Your rent won't necessarily count unless you make sure it does. And the sooner you take credit for your payments, the better.

Here's how to get started based on a few tips from Experian, the Consumer Financial Protection Bureau (CFPB), and FICO:

  • Ask your landlord or property manager if your rent is being reported. If it's not, opt in. 
  • If your landlord doesn't offer rent reporting, there are services available. Be sure to check fees and which bureaus they provide your data to.
  • Check your credit reports for errors. Mistakes happen and fixing them is one of the quickest ways to strengthen your profile. The CFPB offers step-by-step instructions on how to fix errors on your report.
  • Follow basic, important credit rules. Pay your bills on time, keep your card balances low, and don't apply for a bunch of new credit at once.
  • Don’t close any accounts - even if you have paid them off and don't use them often.
  • Diversify your profile by getting a secured credit card or becoming an authorized user on someone else's account to help you build history beyond rent.

These steps take a little time and effort, but it could be worth it if it starts building up your credit history. 

Just remember, not every lender uses the same scoring model and there are more changes on the horizon. So, the sooner you get credit for the work you do, the better. 

Even if you're not sure when you might be ready to buy a home, talking to a lender is a good place to start. A professional loan officer will help you make a plan and help you figure out a timeline to get ready to officially apply and buy.

In Conclusion

The credit landscape is changing, but action is required on your part. You have to take credit for what you do. And the sooner you get started, the better.

Ready to see where you stand? A quick conversation with a loan officer costs you nothing and could show you you're closer to owning a home than you think.